- October 21, 2026
- Capitree Asset LLP
“India’s Stock Market Paradox: If Domestic Money Is Flowing In, Why Are Investors Struggling?”
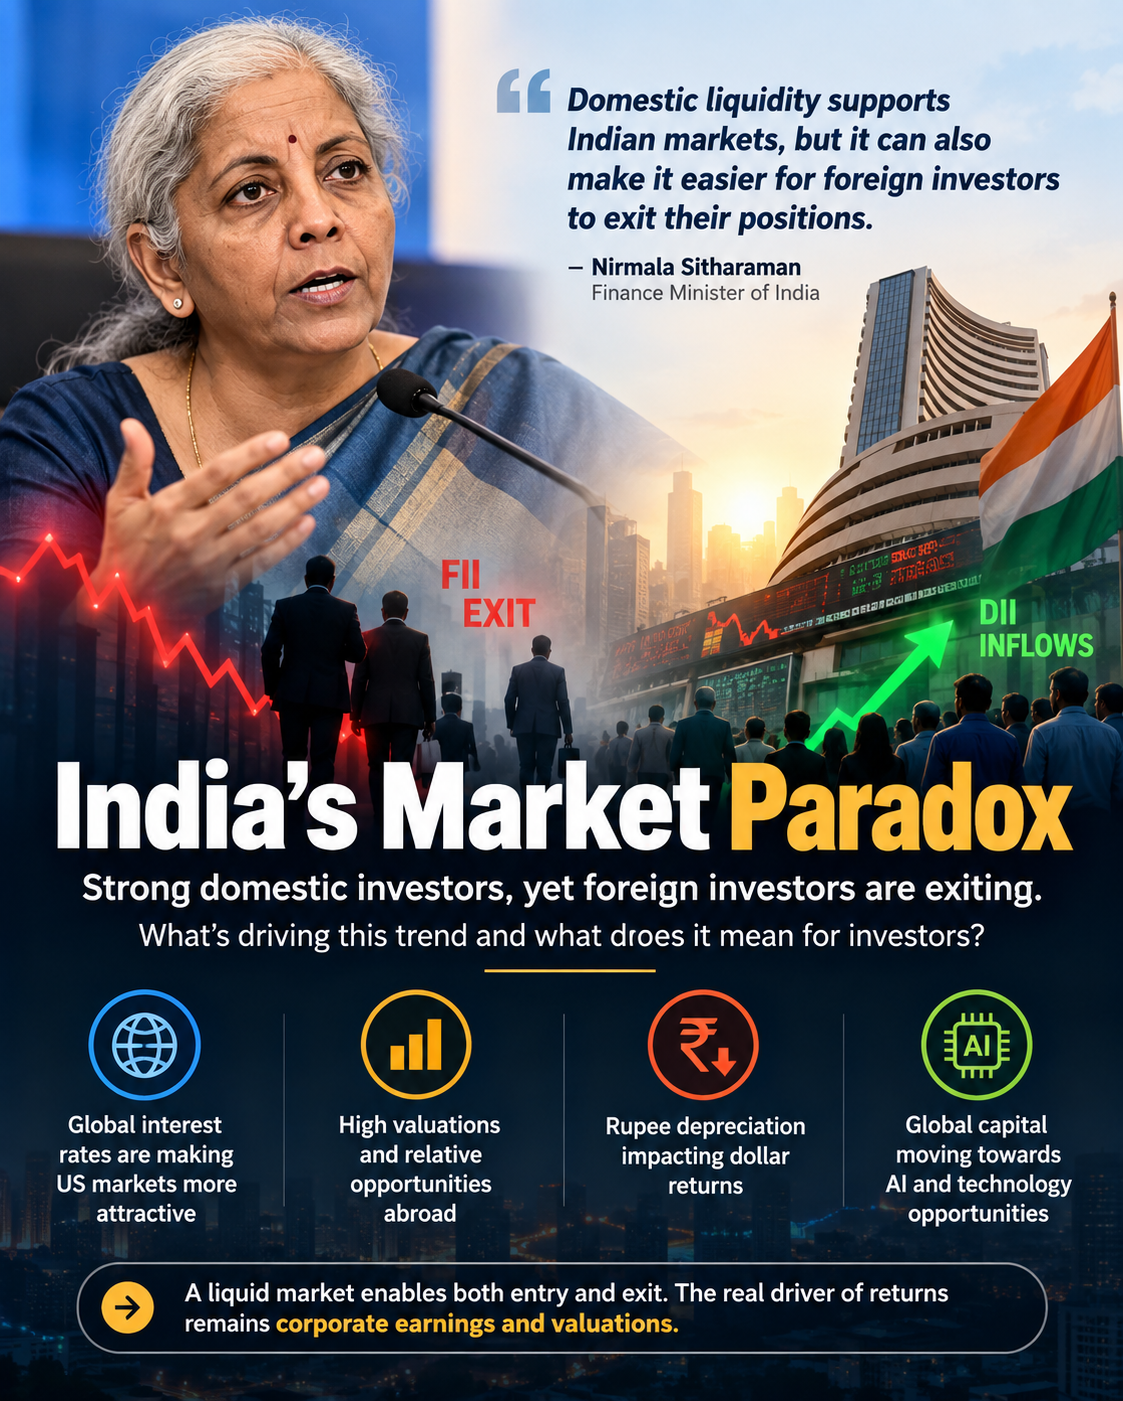
India’s Stock Market Paradox: When Liquidity Supports Exits More Than Growth An investor’s perspective on Finance Minister Nirmala Sitharaman’s recent comments on Indian equities. India’s stock market is facing a question that goes beyond daily market movements: If domestic investors continue investing, why are Indian equities struggling to deliver strong returns? On October 19, 2026, Finance Minister Nirmala Sitharaman highlighted a potential paradox in the Indian equity market. While domestic liquidity continues to support the market, the same liquidity can make it easier for foreign investors and existing shareholders to exit their positions. Her comments came amid sustained foreign portfolio investor (FPI) selling and a period of weakness in benchmark indices. She also identified global capital moving towards the United States and artificial intelligence-linked opportunities as a concern for India. Source: NDTV Profit — The Liquidity Paradox 1. The liquidity paradox: Who is buying, and who is selling? India has developed a deeper domestic investment base, supported by mutual fund contributions and participation from retail investors. However, domestic buying does not automatically translate into rising share prices when substantial selling pressure persists. Consider the market dynamics: Domestic investors: Continue allocating money to equity mutual funds and other market instruments. Foreign investors: Reassess their allocations based on global interest rates, currency movements, relative valuations and investment opportunities elsewhere. Existing shareholders: May use strong domestic demand to sell shares through public markets. New investors: Must evaluate whether the prices they pay are justified by future earnings growth. The result is a market in which liquidity remains available, but the direction of prices depends on the balance between buying demand, selling pressure and valuations. The important distinction is that liquidity makes transactions easier; it does not guarantee attractive returns. 2. Why is foreign capital moving away from India? Foreign investors compare India with other markets rather than evaluating the country in isolation. Several factors influence their decisions: Global interest rates: Higher US Treasury yields can make dollar-denominated investments more attractive relative to emerging-market equities. Currency depreciation: A weakening rupee can reduce foreign investors’ dollar-denominated returns, even when their Indian holdings perform reasonably well in local currency. Valuation concerns: If Indian equities trade at a premium to comparable markets, investors may demand stronger earnings growth to justify that premium. Artificial intelligence and technology opportunities: Global capital has increasingly focused on markets with significant exposure to AI-related companies, including semiconductor and technology businesses. These factors can influence capital allocation even when India’s domestic economic fundamentals remain relatively resilient. The finance minister’s remarks highlight a strategic challenge: India must remain competitive not only in attracting capital but also in generating returns that justify long-term investment. 3. Does domestic liquidity create a false sense of security? Domestic participation is a structural strength for Indian markets. Regular mutual fund inflows can help absorb selling pressure and reduce dependence on foreign investors. However, there is an important distinction between market resilience and market performance. A market can remain liquid and functional while delivering disappointing returns if valuations are elevated, earnings growth slows, or selling pressure persists. Domestic investors should therefore avoid assuming that sustained mutual fund inflows will automatically protect their portfolios from corrections. Similarly, foreign selling should not automatically be interpreted as a rejection of India’s long-term economic prospects. Capital flows are influenced by global portfolio decisions, liquidity requirements and relative opportunities. The real test is whether corporate earnings and cash flows can support the prices investors are paying. 4. What does this mean for investors? For long-term investors, the finance minister’s comments offer three practical lessons. First, separate economic growth from stock market returns. A growing economy creates opportunities, but shareholders earn returns based on the businesses they own, the prices they pay, and the cash flows those businesses generate. Second, pay attention to valuations. Strong narratives around infrastructure, digitalisation, manufacturing and AI do not make every company in those sectors an attractive investment. Valuation discipline remains essential. Third, diversify intelligently. A portfolio concentrated in a handful of expensive stocks or sectors may face significant volatility. Investors should assess diversification across businesses, sectors and asset classes in line with their goals and risk tolerance. For investors using systematic investment plans, market weakness can provide opportunities to accumulate quality businesses at more reasonable valuations. However, an SIP does not eliminate the risk of losses, and investment choices should still be based on fundamentals and financial objectives. 5. What should policymakers and market participants focus on? India’s long-term objective should not simply be to retain foreign capital at any cost. It should be to create an environment in which both domestic and international investors can identify productive opportunities. Three areas deserve attention: Corporate earnings quality: Sustainable profit growth, transparent disclosures and disciplined capital allocation. Market competitiveness: Predictable regulation, reasonable transaction costs and an efficient investment environment. Productive capital formation: Encouraging investment that supports business expansion, innovation, infrastructure and employment. Capital gains taxation and securities transaction tax are also relevant to investor sentiment. However, tax relief alone cannot guarantee sustained market appreciation if earnings, valuations and global conditions remain unfavourable. My view: Liquidity is the mechanism, not the complete explanation The finance minister’s comments identify an important feature of modern equity markets: the same liquidity that enables investors to enter positions also enables them to exit quickly. But liquidity should not be treated as the sole explanation for weak market returns. Foreign outflows, relative valuations, currency movements, global investment trends and corporate earnings all matter. India’s domestic investor base is an advantage, but it cannot indefinitely compensate for weak earnings or excessive valuations. Ultimately, the market needs more than money flowing into financial instruments. It needs capital allocated to productive businesses capable of generating sustainable earnings and cash flows. For investors, the key question is not merely whether money is entering or leaving the market. It is whether the underlying businesses are creating enough value to justify their valuations. That is the distinction between following market liquidity and investing with conviction. Aakash Bisht, Strategic Consultant Disclaimer: This article